

If you run a business, you’ve likely come across various insurance coverages to protect your operations. One type you may not be familiar with is Hired and Non-Owned Auto Insurance (HNOA). It’s an important coverage that can safeguard your business from unexpected liabilities. Let’s break it down in simple terms and explain why it’s a must-have for many businesses.
What is Hired and Non-Owned Auto Insurance?
Hired and Non-Owned Auto Insurance provides liability coverage for vehicles your business uses but does not own. It comes into play in two main scenarios:
-
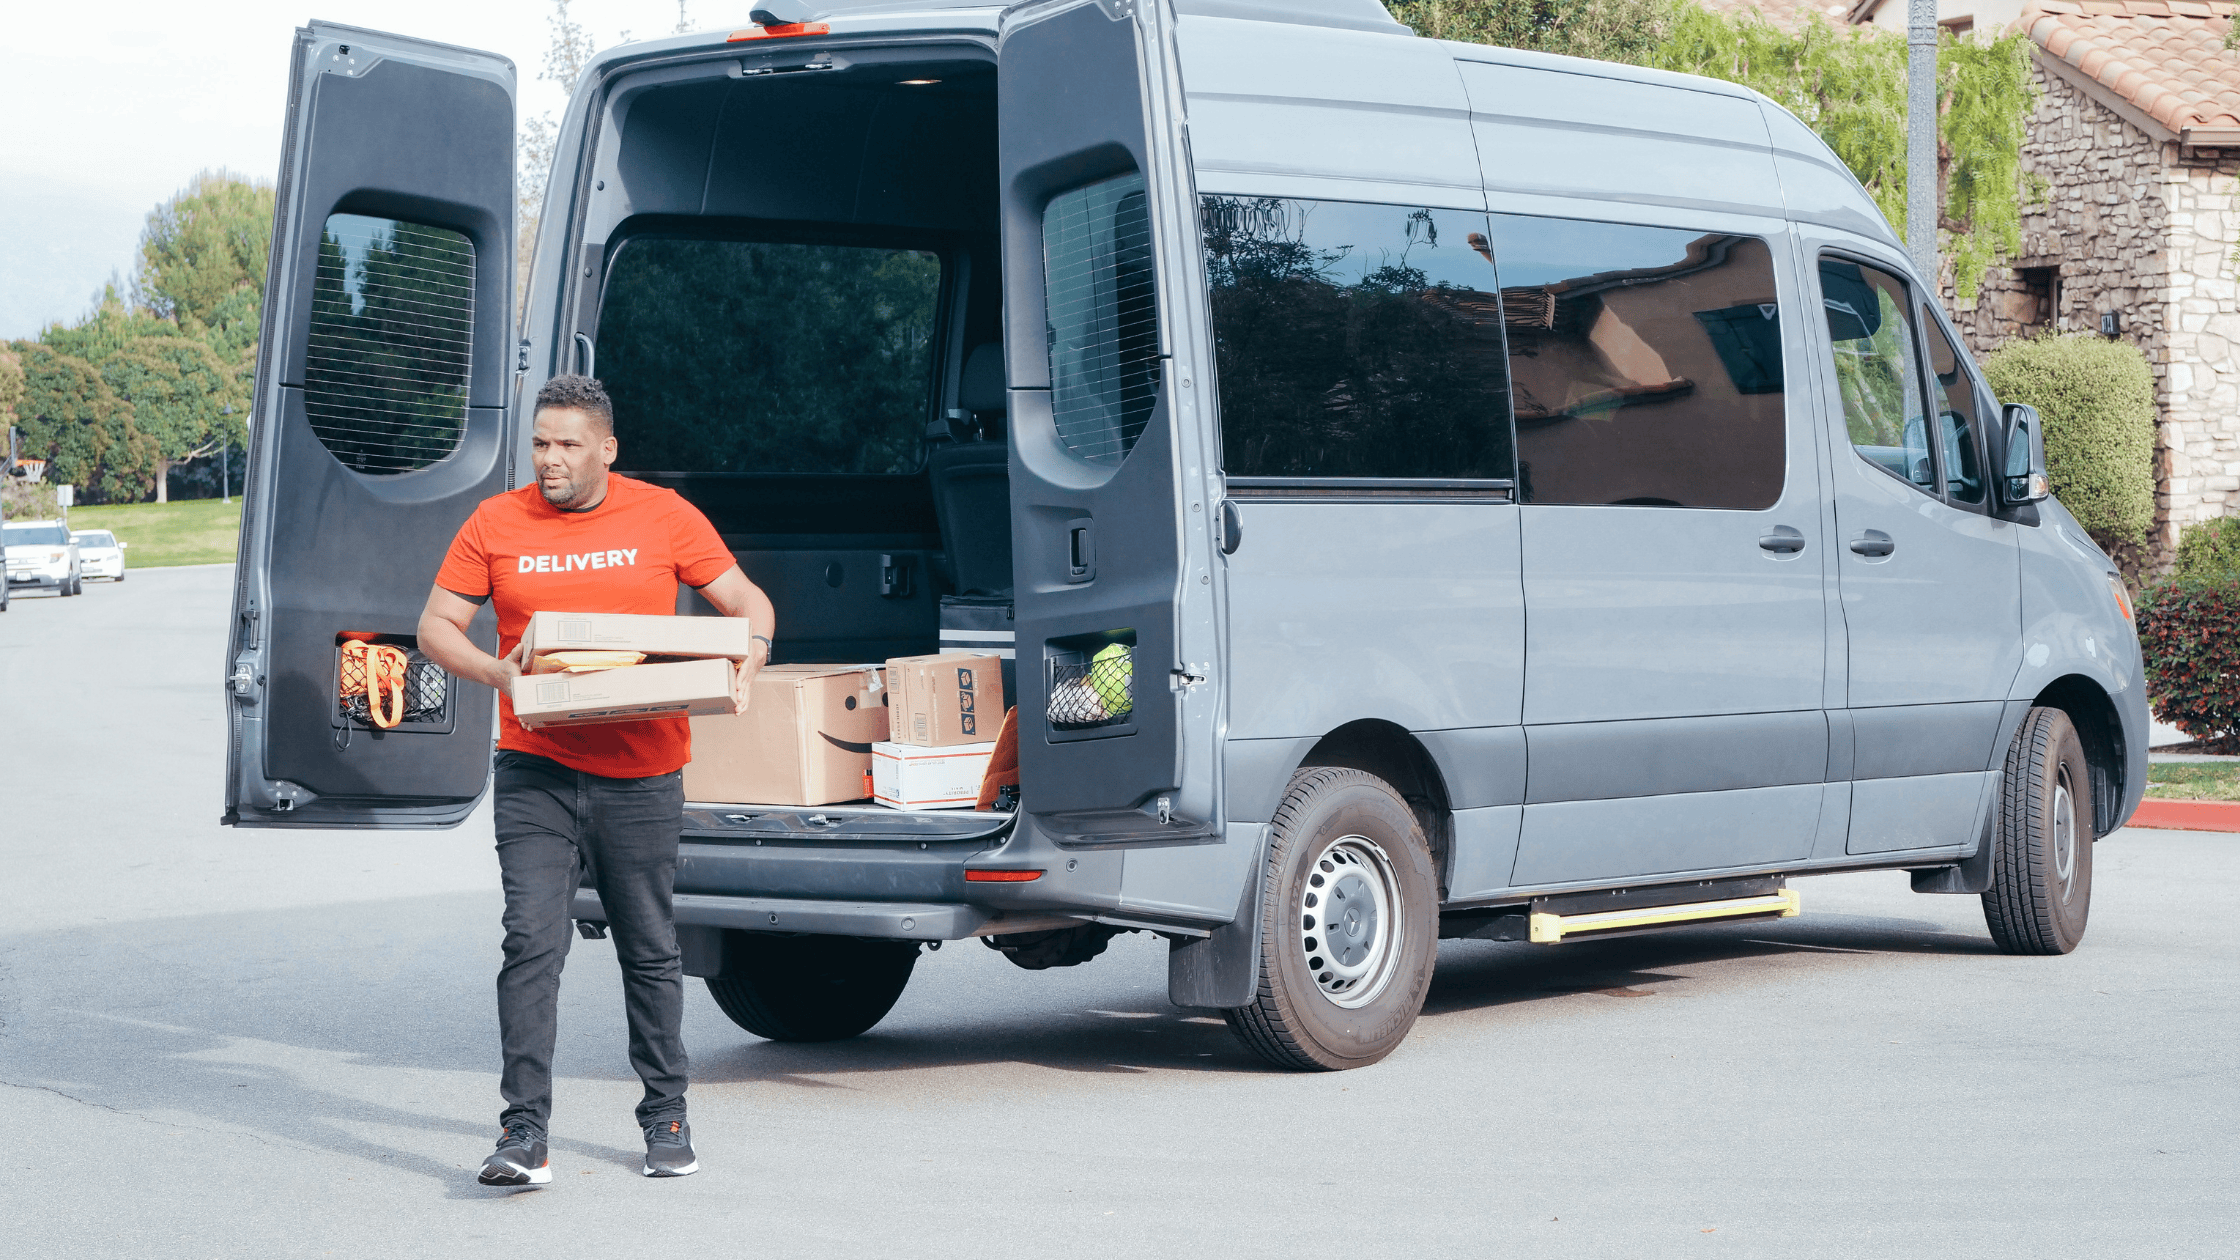
Hired Vehicles: These are vehicles you rent, lease, or borrow for business purposes. For example, renting a van for a delivery or leasing a car for a temporary project.
-
Non-Owned Vehicles: These are vehicles owned by your employees or contractors but used for your business. For example, if an employee uses their personal car to run errands for your business or make deliveries.
This insurance covers liability for property damage or bodily injury caused by these vehicles while they are being used for your business.
What Does HNOA Cover?
HNOA typically provides:
-
Liability Coverage: Covers costs if your business is held responsible for injuries or property damage caused by the hired or non-owned vehicle.
-
Legal Defense: Covers legal fees and expenses if you’re sued after an accident involving a hired or non-owned vehicle.
What It Does NOT Cover:
-
Physical damage to the vehicle itself (you’d need separate coverage like rental car insurance for this).
-
Personal use of vehicles.
Why is Hired and Non-Owned Auto Insurance Important?
Many business owners mistakenly believe they don’t need HNOA because they don’t own company vehicles. But if your employees or contractors ever use their own vehicles for work purposes, you could be held liable for accidents. Here’s why this coverage is critical:
-
Protects Your Business from Lawsuits: If an employee causes an accident while driving their own car for work, the injured party may sue your business for damages. Without HNOA, you’d have to cover these costs out of pocket.
-
Fills Gaps in Personal Insurance: Your employee’s personal auto insurance might not fully cover accidents that occur while they’re using their vehicle for business. HNOA acts as a backup to cover liabilities.
-
Required by Contracts: Some clients or partners may require you to have HNOA coverage before entering into agreements, especially if your business involves transportation or delivery services.
-
Covers Temporary Needs: If your business occasionally rents or leases vehicles, HNOA provides coverage without requiring a full commercial auto policy.
Who Needs HNOA Coverage?
Hired and Non-Owned Auto Insurance is essential for:
-
Businesses that use rental vehicles for temporary needs.
-
Companies that rely on employees or contractors to drive their personal cars for deliveries, client meetings, or errands.
-
Organizations without a fleet of company-owned vehicles but still require vehicles for day-to-day operations.
Practical Example
Let’s say you own a catering business. You don’t have company-owned delivery vans, so your employees use their personal cars to deliver food to events. One of your employees causes an accident while making a delivery. The injured party sues your business for medical bills and property damage.
Without HNOA, you’d have to pay for these costs out of pocket. With HNOA, your insurance policy would cover the liability, protecting your business’s finances.
How to Get HNOA Coverage
Most business insurance providers offer Hired and Non-Owned Auto Insurance as an add-on to general liability or business owner policies. When shopping for coverage, be sure to:
-
Assess Your Needs: Determine how often your business uses hired or non-owned vehicles.
-
Work with an Expert: An insurance agent can help tailor coverage to your specific business risks.
-
Review Policy Limits: Ensure the coverage limits are high enough to protect your business from significant liabilities.
How to Choose the Right Policy
Selecting the right Non-Owned and Hired Auto Liability Insurance policy requires careful consideration of your business’s specific needs. Follow these steps:
-
Assess Vehicle Use: Determine how often and in what capacity your business uses non-owned or hired vehicles.
-
Work with an Independent Agent: Partner with an experienced agent who can compare multiple carriers and recommend the best coverage.
-
Review Policy Limits and Exclusions: Choose appropriate liability limits to ensure full protection and understand any exclusions in the policy.
Why Partner with Wise Insurance Agency?
At Wise Insurance Agency, we specialize in tailoring insurance solutions to the unique needs of Massachusetts businesses. Here’s why businesses in Ashland, Framingham, Natick, Wellesley, Brookline, and beyond trust us:
-
Comprehensive Coverage Options: We offer access to multiple carriers, providing customized policies that suit your business operations.
-
Proactive Support: Our team is with you every step of the way, from selecting the right policy to advocating on your behalf during claims.
Protect Your Business Today
Non-Owned and Hired Auto Liability Insurance is not just a safeguard—it’s a vital part of a strong business insurance portfolio. Don’t leave your business vulnerable to unexpected liabilities. Contact Wise Insurance Agency at 508-722-7100 or email us at for a personalized consultation.
Let us help protect what you’ve worked so hard to build. With Wise Insurance Agency, you’re never on your own when it comes to insurance.